Monthly Mortgage Digest
Rates Hit 7.40% as Sellers Pay Up, Buyers Gain Ground, and CMA Requests Jump 51%

The Monthly Mortgage Digest
Rate trends, homeowner behavior, and what it means for your pipeline.
Mortgage rates hit 7.40% this month, the highest since November 2023, and the Fed raised rates on September 16 for the first time in more than three years.
Deals are still closing, though. 44.7% of sellers paid concessions this summer, one in five listings took a price cut in September, and CMA requests inside Homebot jumped 51%. Buyers are winning price cuts and seller credits, and more homeowners want to know what their home is worth before they list. The real question is whether you're the one showing them how to make the payment work.
Below we're covering how lenders and agents are getting deals done at 7.40%, from seller-paid buydowns to the comeback of the ARM, plus the 2,001 homeowners in your database who just asked what their home is worth.
What's Happening in the Market
Rates Hit 7.40% - The Highest Since Late 2023
The 30-year fixed averaged 7.40% in Freddie Mac's October 15 survey, holding flat after a jump from 7.28% the week before. A year ago it was 6.27%. When breaking down the math, that means on a $400,000 loan, principal and interest run about $2,770 a month at 7.40%, roughly $300 more than at last fall's rate.
The Fed added fuel to the fire on September 16 with a quarter-point hike to 3.75%-4.00%. To make matters worse, most officials expect another hike by year end. Twelve of the 18 Fed forecasts call for at least one more increase in 2026. Translation: nobody should be building a sales pitch around rates falling this fall.
For Lenders
- Check for assumable loans. FHA and VA loans can be taken over at the seller's rate, and AssumeList estimates about 6 million homes carry an assumable loan under 5%. Have a plan for covering the seller's equity (cash or a second loan) before your buyer falls for the house.
- Show three payment options. Put every pre-approval side by side: a 30-year fixed with a seller-paid permanent buydown, a 2-1 temporary buydown, and a 5/1 ARM, which averaged 6.54% against 7.50% for the 30-year fixed. Let the buyer pick the payment that fits their plans.
For Real Estate Agents
- Negotiate what you can control. Buyers who paused for a cut are now looking at about $300 more a month than last fall. Shift the talk to what they can negotiate today: price, concessions, and repairs.
- Prep clients in escrow for October 28. Make sure they've talked to their lender about locking so a Fed headline doesn't rattle a signed deal.
For Both
- Lead with the monthly payment. It's a number clients can plan around at today's rate, and the Fed meets again October 28.

Purchase Apps Down 16% - Buyers Are Hunting for a Lower Payment
MBA purchase applications sat 16% below last year for the week ending October 9, and the average contract rate climbed to 7.50%. Refi applications ran 56% below a year ago. The buyers who are still applying are getting creative about the payment.
ARMs made up 10.5% of applications, the highest share in a year. MBA's Joel Kan said borrowers continue to rely more on ARM loans to help lower their monthly payments. ICE sees the same thing: ARMs hit more than 11% of rate locks, the most in nearly four years, and 50% of borrowers paid points in August, the highest since early 2025. Buyers are buying down their own rate with their own cash.
For Lenders
- Spell out the ARM reset. Put an ARM next to the 30-year fixed on every pre-approval, with the payment after the reset in plain English. ICE flags about 74,000 seven-year ARMs from 2020 facing a median jump of about $1,066 a month in 2027, so the exit plan matters as much as the start rate.
- Find the seller's money first. If half your borrowers are paying points, a concession that funds a permanent buydown keeps the buyer's cash in their pocket for closing.
- Keep every 7% loan in your database. Each one you close this fall is a future refi, so you're the first call when rates move.
For Real Estate Agents
- Pair serious buyers with a lender early. Fewer applications means fewer buyers at the open house, and the ones who show up are serious. Bring in a lender who can show an ARM and a buydown side by side at the first showing.
- Ask how they'll cover points. If the answer is "my savings," that's your cue to negotiate seller credits.
For Both
- Answer the same day. The buyers still applying are serious about moving, so respond with a payment option ready to go.
44.7% of Sellers Paid Concessions - Buyers Have the Upper Hand
Redfin found 44.7% of home sales in the three months ending August came with a seller concession, up from 42.6% a year earlier and the highest August share since at least 2020. Another 15.8% of sales came with both a price cut and a concession, a record for August. Redfin called August the strongest buyer's market in its records, which go back to 2013.
It's most extreme in the Sun Belt. Concessions showed up in 72.8% of Atlanta sales, 67.9% in Charlotte, and 67.4% in Phoenix. In San Jose it was 4.2%. Builders are offering $10,000 to $20,000 and buying down rates to move inventory. Resale sellers are competing with that.
For Lenders
- Hand agents a concession menu. Build one page showing what $10,000 of seller money does as a permanent buydown, a temporary buydown, or closing costs. Agents write what they can explain.
- Check contribution limits early. Confirm interested-party contribution limits for the loan program before the offer goes in, so a generous concession doesn't get trimmed at underwriting.
For Real Estate Agents
- Ask for concessions in the first offer. Especially in Sun Belt markets, ask for the money as rate buydown dollars and have your lender show the buyer the new payment.
- Compare a credit to a price cut. Before the next price cut on a listing, walk your seller through both options. Seller money aimed at the buyer's rate can do more for the monthly payment than the same dollars off the price.
For Both
- Agree on the concession before the offer. Get on the same page with your lender or agent partner so the request and the payment it creates are already worked out.
Inventory Hits 1.16 Million - The Closest to Normal Since the Pandemic
Realtor.com counted 1,161,615 active listings in September, up 5.4% from last year. The gap to 2019 levels shrank to 9.1%, the first time it has dipped below 10% in this recovery. The median list price fell 1.4% to $419,250, the 11th straight month of annual declines, and 20.8% of listings took a price cut, the highest September share since 2018.
Sales are holding on. NAR reported existing-home sales up 1.5% in September with a median price of $417,500 and 4.8 months of supply. First-time buyers made up 31% of sales. Lawrence Yun said higher inventory and longer days on market give buyers improved negotiating power. Where you sit matters: listings jumped 11.6% in the Northeast and 11.3% in the Midwest, while price cuts topped 33% in Salt Lake City and 32% in Denver.
For Lenders
- Pre-approve first-time buyers now. They're 31% of sales. Build in a concession plan and any down payment assistance they qualify for, so they can move when the right price cut shows up.
- Know your local numbers. A buyer in Denver has a very different negotiation in front of them than a buyer in Buffalo.
For Real Estate Agents
- Price it right the first time. One in five listings is cutting price. Walk sellers through fresh comps before you list.
- Use the extra time to negotiate. Buyers have more choices and more time. Push for repairs and credits, then set clear deadlines so they don't wait their way out of the right house.
For Both
- Read your local market. Price cuts topped 30% in Denver and Salt Lake City while New York sat near 10%, so the national number only tells part of the story.
Insurance Hits $209 a Month - Switchers Saved $440 a Year
ICE puts the average property insurance bill at a record $209 a month, nearly 80% more than at the start of 2020. It now eats 9.6% of the average mortgage payment. The good news: growth is slowing, with premiums up 8.7% from last year after peaking at 15.1% in late 2024.
The bigger story is shopping. Homeowners who switched carriers cut premiums by a record 6.6%, while those who stayed put paid 10.4% more. That's a $440 a year difference. In New Orleans, insurance is 24.3% of the mortgage payment. In San Jose, it's 4.3%.
For Insurance Agents
- Lead renewals with what switching saves. A client who stays put is on track for a 10.4% increase, and you can show them the alternative before someone else does.
- Get in at pre-approval. Ask your lender and agent partners to loop you in early. At 9.6% of the payment, a real quote up front keeps deals from stalling late.
For Lenders
- Qualify with a real quote. Use an actual insurance quote from day one, especially in high-premium markets where insurance can be a quarter of the payment.
- Build insurance into the payment. At 9.6% of the average payment, it can decide whether a buyer qualifies.
For Real Estate Agents
- Quote insurance before the offer. In a high-premium market, a re-shop worth about $37 a month can be the difference between a buyer qualifying or walking.

Get the Monthly Mortgage Digest straight to your inbox each month
What This Looks Like Inside Homebot
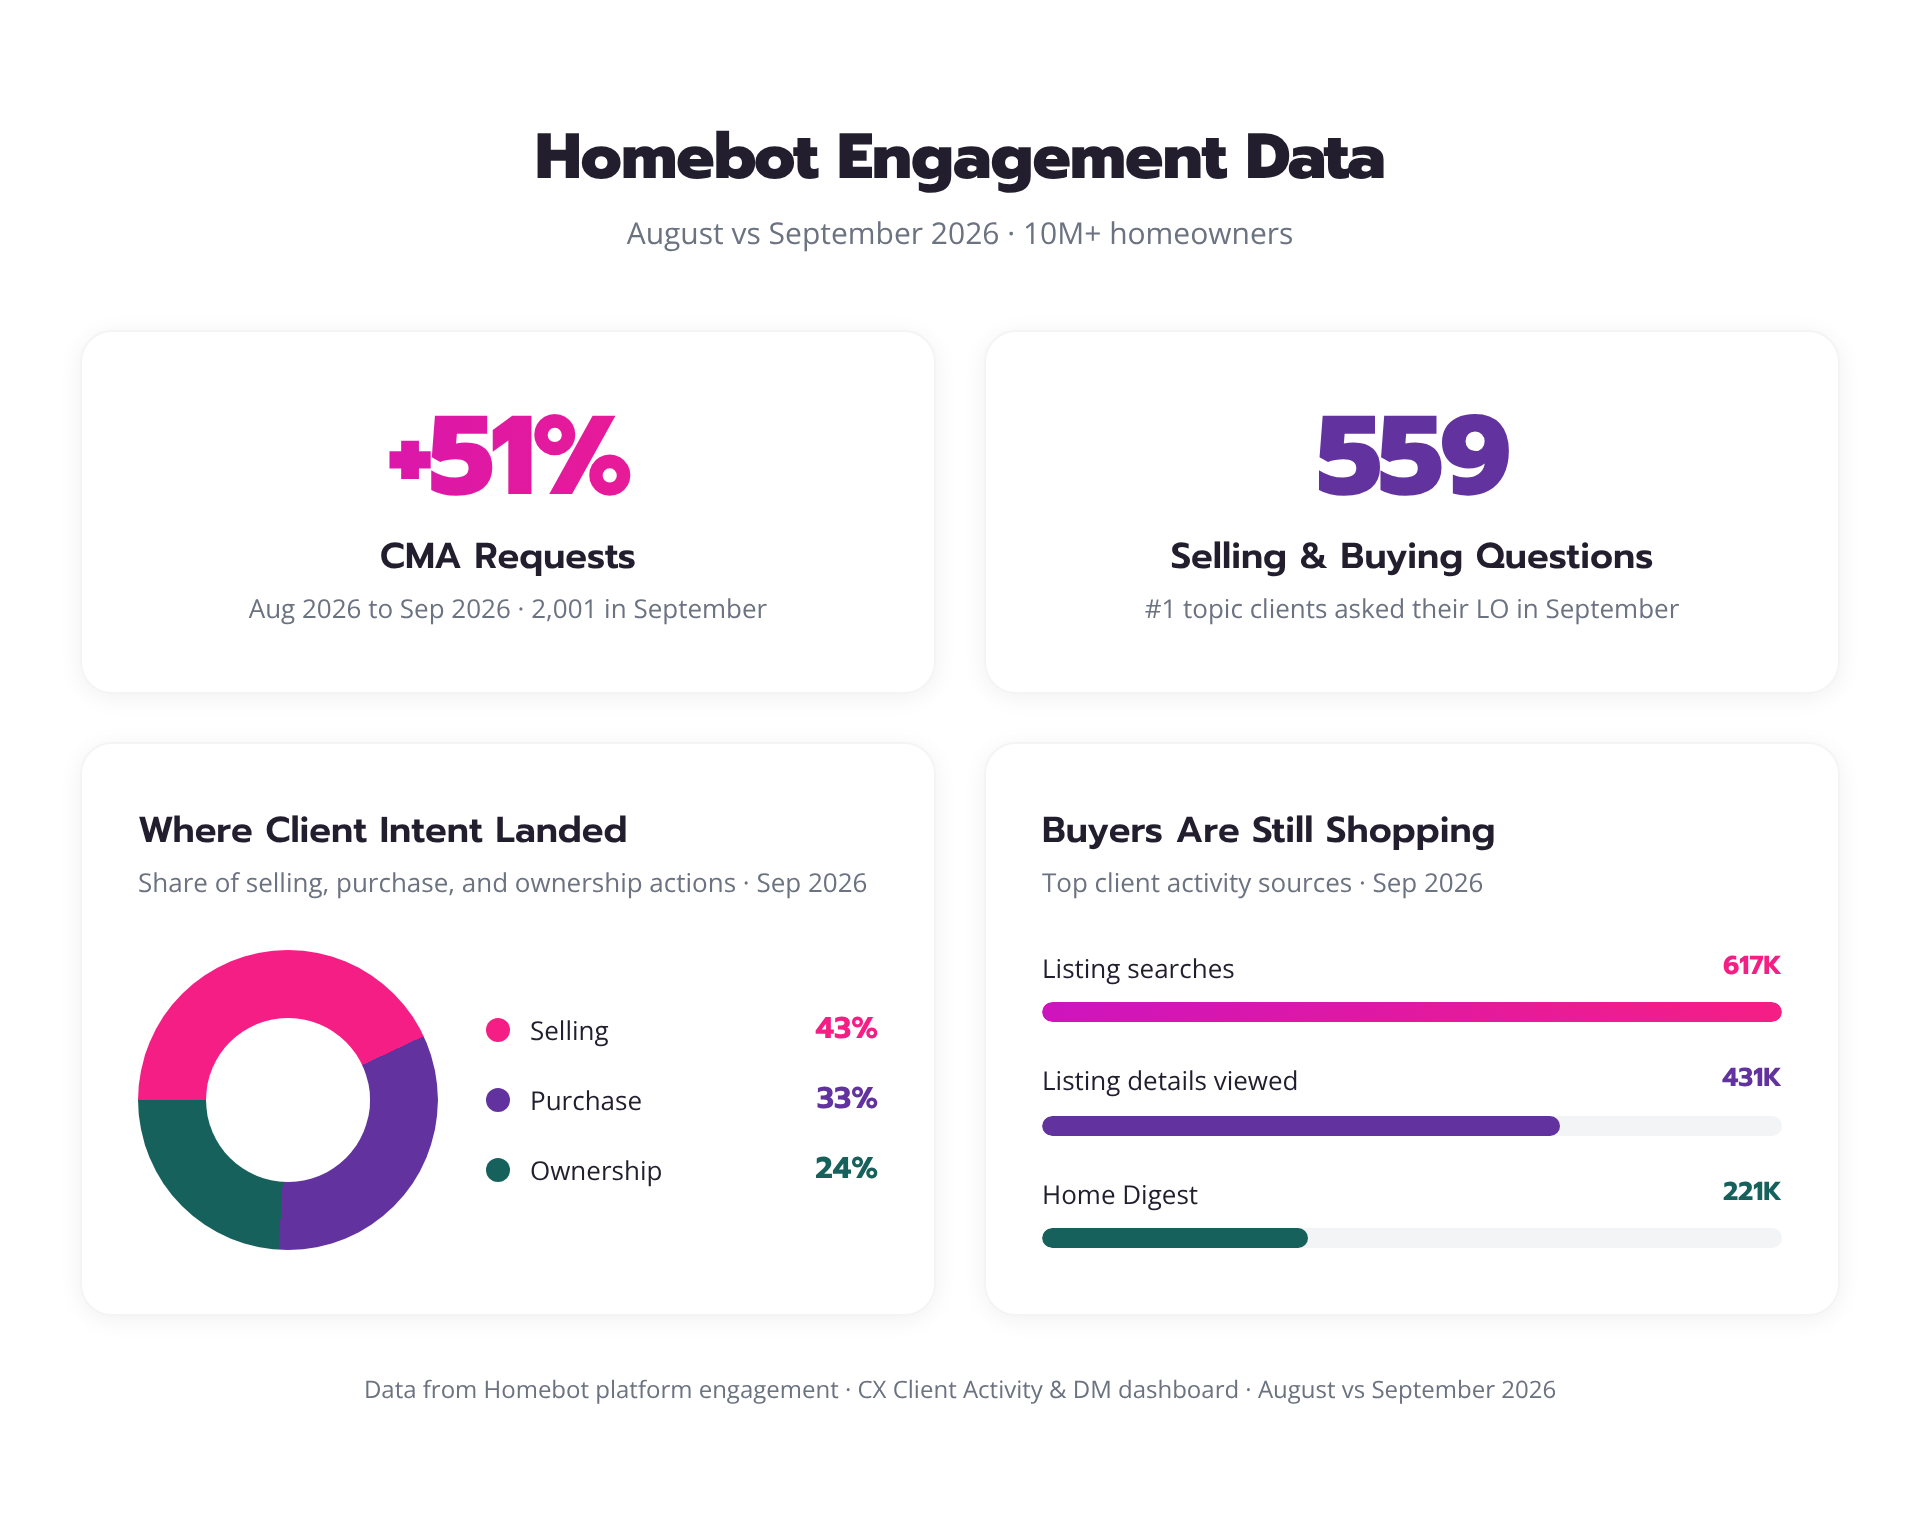
Across Homebot's 10M+ homeowners, September brought 1.37 million client actions, and the intent was concentrated on one thing: moving. Homeowners ran CMAs, asked their loan officer about selling and buying, and kept searching listings at 7.40%. Here's what your database is telling you.
1. CMA Requests Up 51% - Sellers Want a Real Price
Homeowners ran 2,001 CMAs in September, up from 1,328 in August. That lines up with what the market is telling them: 1.16 million listings and one in five taking a price cut. Sellers know they're competing, and they want a real number before they decide. That's a full call list for agents this month, with a move-up payment conversation for the lender right behind it.
2. Selling and Buying Was the #1 Question - 559 Times
Homeowners messaged their loan officer about selling and buying 559 times in September, far ahead of any other topic. Selling was also the top client action at 1,180, ahead of purchase (902) and ownership (645). At 7.40%, "can I afford to move?" comes down to two numbers: net proceeds on this home and the payment on the next one. The LO who sends both first gets the deal.
3. Buydowns Are Still the Top Financing Question
Buydowns as a seller concession stayed the top financing question clients asked in September. That matches the 44.7% of sales coming with concessions and the 50% of borrowers paying points. Short-term rentals also showed up with 37 questions, a sign some owners are weighing whether to keep their home and rent it out instead of selling. Both are conversations about making a payment work at today's rates, and both start with the lender.
4. 617,000 Listing Searches - Buyers Haven't Left
Clients ran 617,000 listing searches and opened 431,000 listing details in September. Another 220,000 actions came from the Home Digest, where owners check their value and equity. Buyers are still shopping with rates over 7%, and owners are watching what they've built. For the owner sitting on a 3% rate, that equity is the start of a HELOC or move-up conversation.
5. Personal Outreach Gets Answered - 52 Video Replies
When loan officers sent a personal video email, clients replied 52 times in September, the second most common DM topic. Clients write back when someone reaches out to them directly. You don't need a rate cut to justify a check-in this fall. The engagement is already there, and a 60-second video is enough to start the conversation.
What to Do Next
Lenders
- Hand every agent partner a concession menu this week. 44.7% of sellers are paying concessions, and buydowns are still the top financing question in your database. Show what $10,000 of seller money does as a permanent buydown versus closing costs, on one page, so it gets written into the offer.
- Answer the 559 move questions with two numbers. Homeowners asked their LO about selling and buying 559 times in September. Reply with estimated net proceeds and the payment on the next home at 7.40%, so they have real numbers before they talk themselves out of it.
- Put an ARM next to every 30-year quote. ARMs hit more than 11% of rate locks, the most in nearly four years. Show buyers both payments and the reset terms in plain English so they choose with the full picture.
Real Estate Agents
- Call your CMA list. 2,001 homeowners ran a CMA in September, up 51% from August. With 20.8% of listings taking a price cut, bring fresh comps and a pricing plan that gets it right the first time.
- Ask for concessions in every buyer offer. 44.7% of sales came with concessions, and 72.8% in Atlanta. Ask for the money as rate buydown dollars and have your lender partner show the buyer the new payment.
- Send listings to your most active searchers. Clients ran 617,000 listing searches in September. Ask Homebot who is searching most and send them homes with recent price cuts or seller credits on the table.
Insurance Agents
- Re-shop every renewal coming up in the next 60 days. Switchers cut premiums 6.6% while stayers paid 10.4% more, a $440 a year gap. Call before the renewal notice lands and the client starts shopping without you.
- Get a quote into every purchase file at pre-approval. Insurance now averages $209 a month and 9.6% of the payment. Ask your lender and agent partners to loop you in early so the number in the file is real from day one.
- Offer fast quotes in high-premium markets. In New Orleans, insurance is 24.3% of the mortgage payment. Give your lender and agent partners a quick turnaround so insurance never holds up a closing.
For All Three
- Start with the clients already raising their hands. Your Homebot dashboard shows who ran a CMA, who is searching listings, and who asked about buydowns. Begin this week's outreach there.
Closing Thought
The lenders, agents, and insurance pros closing deals at 7.40% are working the people who already raised their hand: the 2,001 homeowners who ran a CMA, the 559 who asked about selling and buying, and the buyers searching listings every night. Homebot surfaces those signals before they become obvious, so you can show up with a buydown menu, a net proceeds number, or a better insurance quote while the client is still deciding.
The clearest signal in a 7% market is the client already asking about their next move inside Homebot. Answer them first.
See what Homebot surfaces in your database: Start free at homebot.ai

Get the Monthly Mortgage Digest straight to your inbox each month